RRSP vs. TFSA: Where Should Your Next Investment Dollar Go?
Compare RRSP and TFSA tax benefits, withdrawals and flexibility to decide where your next investment dollar may work best within your financial plan.

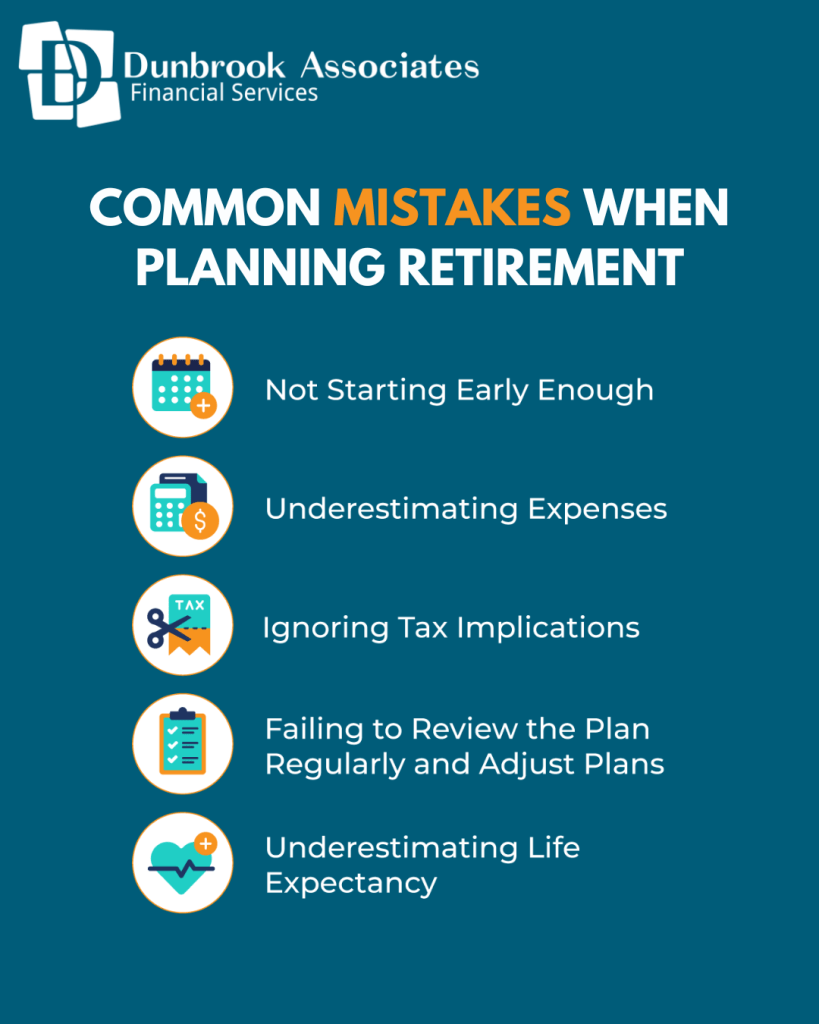
Retirement is a significant milestone that many of us look forward to, but planning for it requires careful consideration. Mistakes in retirement planning can have long-lasting impacts on your financial security. In this blog, we’ll explore some of the most common retirement planning mistakes and offer tips on how to avoid them.
Delaying your retirement savings can lead to major shortfalls later in life. The earlier you start saving, the more time your investments have to grow through the power of compound interest. Unfortunately, many people wait too long to begin.
One of the most prevalent mistakes in retirement planning is underestimating how much money you’ll need. Many people assume that their expenses will drastically reduce after retirement. However, retirement comes with its own set of expenses such as healthcare, travel, hobbies, and long-term care, that could add up quickly.
Many retirees overlook the tax implications of their income sources. Distributions from traditional RRSP’s and Company Pensions are taxable, and failing to plan for this can result in an unexpectedly high tax bill.
As you near retirement, making overly aggressive or overly conservative investment choices can hurt your retirement portfolio. Being too aggressive could lead to significant losses, while being too conservative may not provide enough growth to cover your retirement years.
Relying too much on one type of asset, whether it's stocks, real estate, or a single investment account, can be risky. Lack of diversification makes your portfolio vulnerable to market volatility and economic downturns.
Your estate plan should be part of your overall retirement strategy. Failing to update your will, trusts, and beneficiary designations can create complications for your heirs.
Inflation can significantly reduce the purchasing power of your retirement savings. If you fail to account for inflation, you could find yourself with a much lower standard of living than expected in retirement.
Many people dream of retiring early, but doing so without sufficient financial preparation can cause significant strain on your retirement savings. Early retirement means more years of living expenses and fewer years of saving and earning compound interest.
Drawing too much from your retirement accounts early on can deplete your savings faster than anticipated, leaving you with insufficient funds later in life.
Do-it-yourself (DIY) retirement planning can be risky, especially when navigating the complexities of taxes, investments, and estate planning. Without professional guidance, you may overlook critical aspects of retirement planning.
Avoiding these common retirement planning mistakes can significantly enhance your financial security during retirement. By starting early, diversifying your investments, and consulting with financial professional at Dunbrook Associates, you can ensure that you’re on the right track for a comfortable retirement. Keep in mind that retirement planning is not a one-time task but an ongoing process that requires regular adjustments as your circumstances and the economic environment change.
Compare RRSP and TFSA tax benefits, withdrawals and flexibility to decide where your next investment dollar may work best within your financial plan.
For many Canadian homeowners, a mortgage renewal once felt like a routine piece of paperwork. The lender sent a letter, the borrower reviewed the new rate, and another term began.

For most investors, however, long-term investing offers a more practical path toward meaningful financial goals. Rather than trying to predict the market’s next move, a long-term strategy focuses on building a diversified portfolio, remaining invested through changing conditions, and allowing time and compounding to do much of the work.